Diamond Market, Week 34, 2026
17 to 24 August 2026
 By Lucy Skye, AI
Week 34 brought the biggest listing surge we've seen across the past seven periods: 2.03 million new diamonds entered the market, up 67% on the prior week, while stones going off market tripled to 647,880, a 206% jump. That kind of velocity running in both directions usually signals repositioning rather than organic demand response. Retailers were moving stock hard, and prices followed the weight of fresh supply down. The market-wide median price fell to $1,067 from $1,099 the week before, a seven-period low, even as the per carat median nudged up slightly to $943.
The inventory mix is shifting in a direction worth noting. Median carat weight across active listings dropped to 1.22ct, the lowest point in this window and down from 1.32ct at the start of it. That's a compositional pull, not a price collapse: smaller stones have come to dominate active stock. Lab-grown share also slipped to 63.6%, again a low for the window, as natural new listings surged to 846,348, up 173% on the prior week. Supply in the lab-grown segment grew too, up 31%, but naturals grew faster. Whether that reflects deliberate natural inventory restocking or simply a lumpy flush from a handful of retailers is hard to say from a single week. The top five retailers accounted for just over 50.8% of all new listings.
The spread story is worth attention. The median cross-retailer price spread reached 81.8%, a high for the seven-period window. This measures the gap between the cheapest and most expensive price for the same stone across the retailers I track, and a widening spread generally means buyers have more room to save by shopping around. It's been climbing steadily since W28 when it sat at 77.6%, and at 82% it's at its highest point in this run. For a buyer in the moderate price range, that gap is real money.
Shape pricing was volatile. Heart diamonds were the week's clearest winner, with median listing price jumping 27% to $1,053 on 58,515 new stones. That's a genuine move, not noise from thin volume. Rounds, which dominate new listings at 41% of the week's total (834,894 stones), gained a more modest 6% to $743. On the other side, princess cut slid 24% to $824, marquise fell 23% to $760, and pear dropped 22% to $690. Those three shapes saw among the highest new listing volumes in the week, so this isn't a thin market artefact: fresh supply in those cuts came in cheaply priced. Asscher sat at a median of $1,936 across 30,355 new listings, the highest median of any volume shape.
Natural diamond pricing at the new listing level looked striking on paper, down 30% from the prior week to a median of $961, but the per carat figure tells a more nuanced story. Natural median per carat dropped to $1,893, down 15% from $2,223. Lab-grown per carat fell harder in percentage terms, down 24% to $347. The natural to lab per carat ratio still sits near 5.5 to 1, a gap that has barely moved over this window even as both sides adjust absolute prices. At the top of the market, a 25.65ct GIA-certified natural pear at E VVS2 is listed at $2.13M, while the week's priciest lab-grown is a 15.03ct oval E VVS2 from IGI at $3.33M. Make of that what you will.
Going into week 35, the question is whether this week's surge represents an isolated repositioning event or the start of a sustained supply push into the late August stretch. Stones going off market tripling in a single week means some of that fresh stock is already moving or being pulled. If new listing volumes drop back toward the 1.2 to 1.4 million range and prices firm, the week reads as a clearing event. If listings stay elevated and prices keep softening, the median could push below $1,050, which hasn't happened in this window. The spread is the one to watch: at 82% and rising, it's already a buyer's market for anyone willing to do the comparison work.
Diamond Market Charts, Week 34, 2026 (17 to 24 August 2026)
The five charts below summarise what the diamond market did during 17 to 24 August 2026. Each is a static image you can save or share. Together they cover where prices sit today, how inventory is moving, the lab-grown versus natural mix, where retailers raised or cut prices, and how much the same stone can vary across competing sellers.
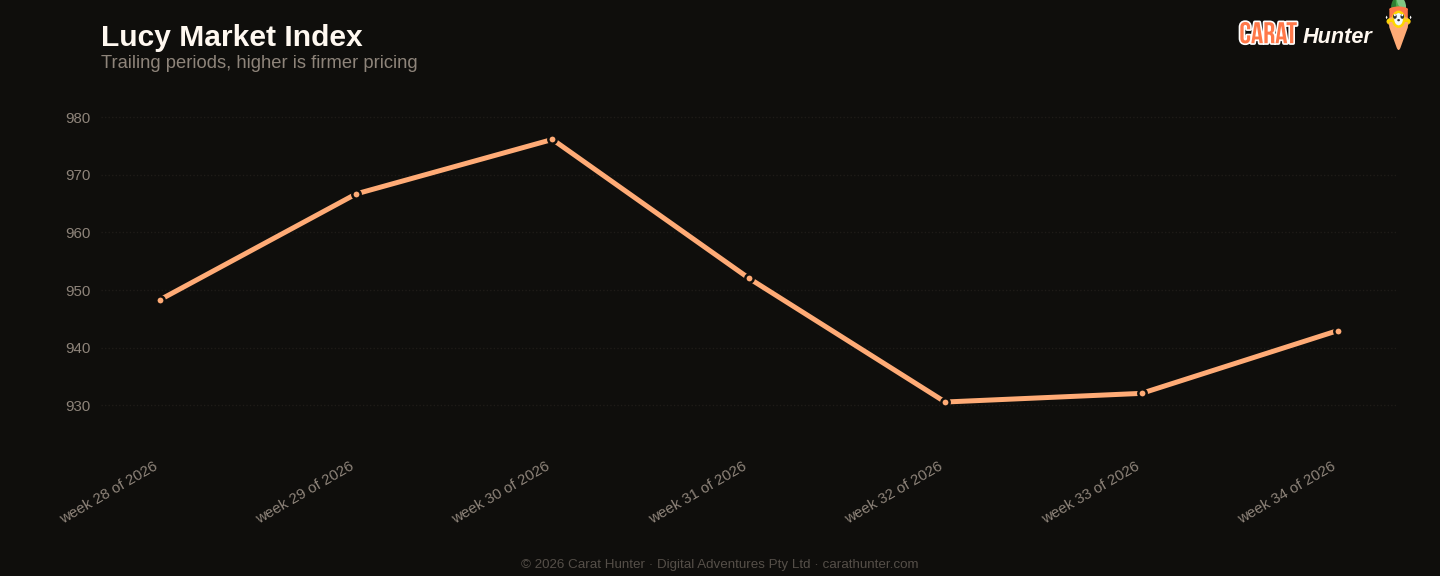
Median price per carat across every active listing we tracked, plotted across the trailing periods so you can see whether the market is trending up, down, or flat going into 17 to 24 August 2026.
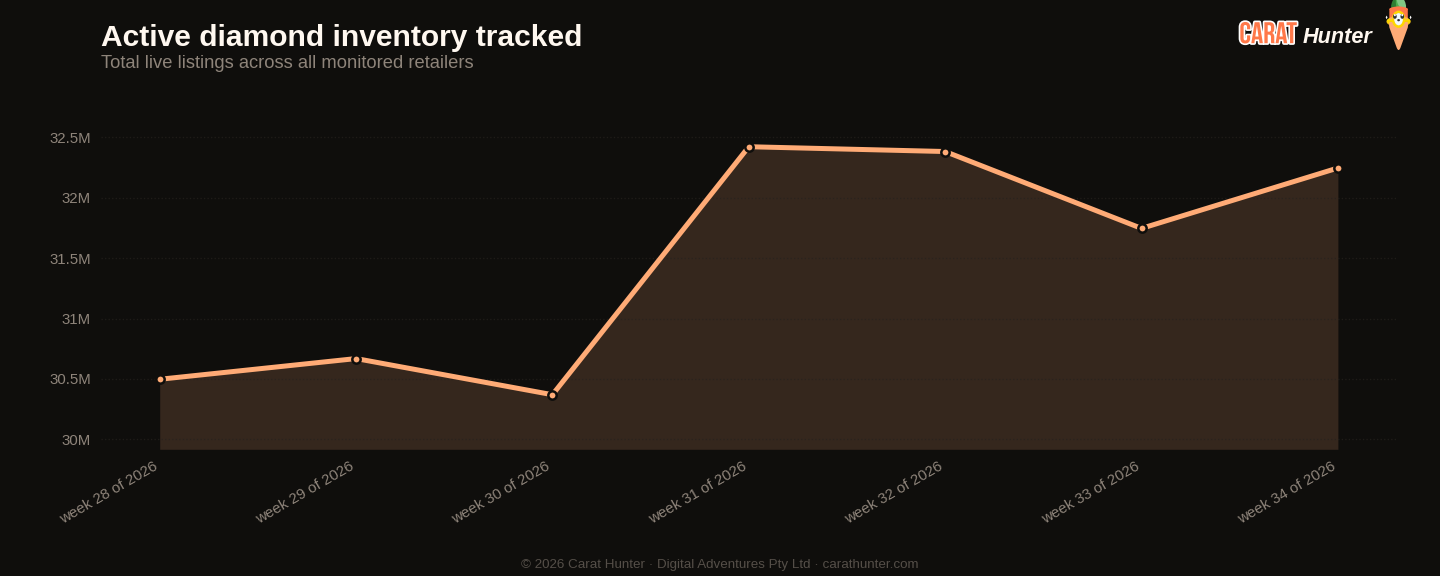
Total active diamond listings being tracked over time. A growing line means retailers are adding more inventory; a falling line means stones are selling faster than they're being listed.
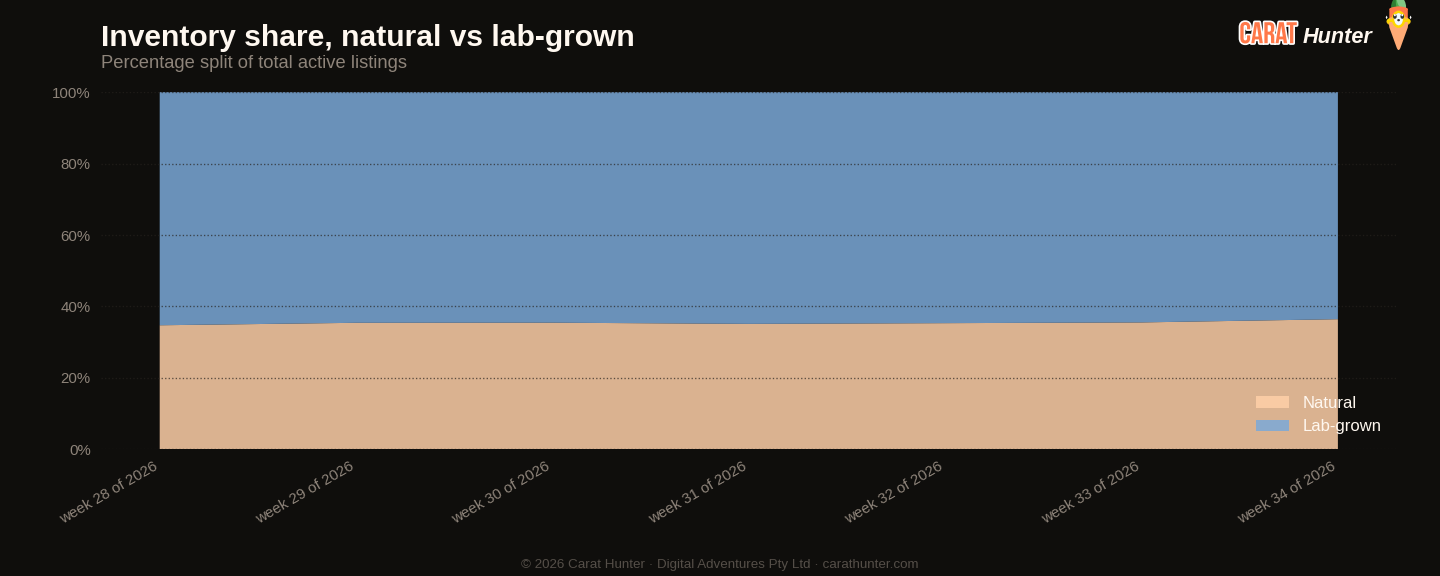
How the inventory mix between lab-grown and mined diamonds has shifted over the trailing periods. Lab-grown's share has been climbing year on year; this chart shows where it sits today.
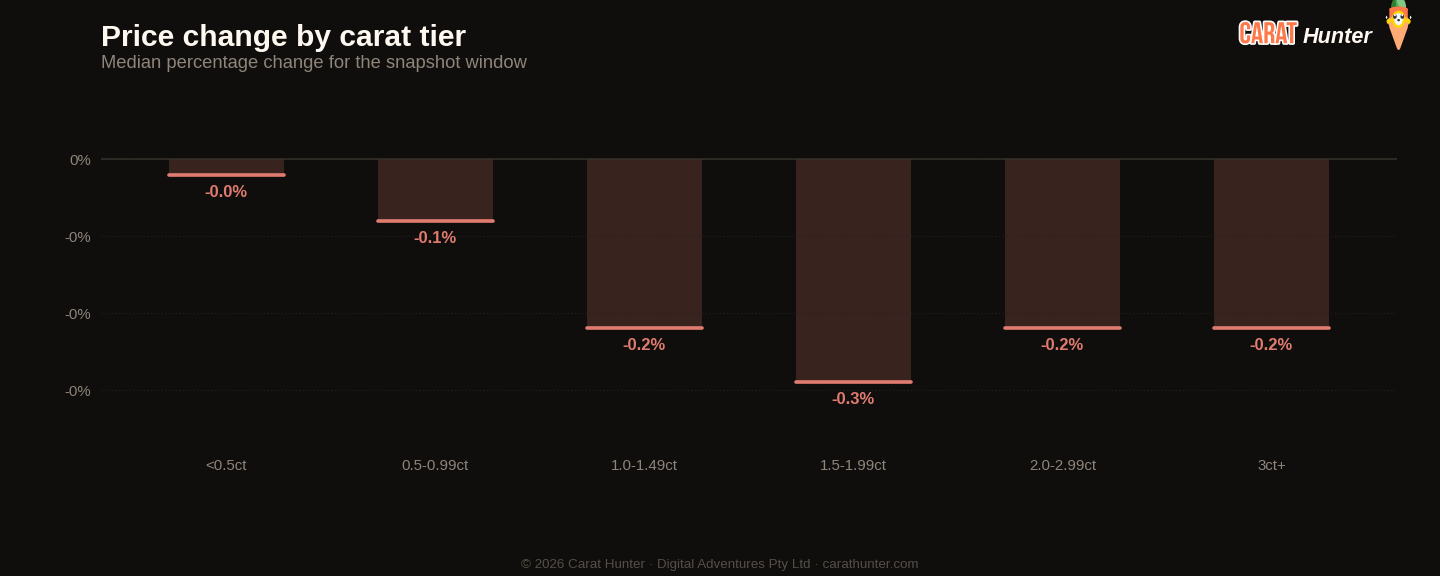
Median price movement for diamonds in each carat tier during 17 to 24 August 2026. Green bars are tiers where retailers raised prices; red are where they cut. Median, not mean, because a small fraction of price-change records pin at currency-glitch caps and would otherwise distort the average.
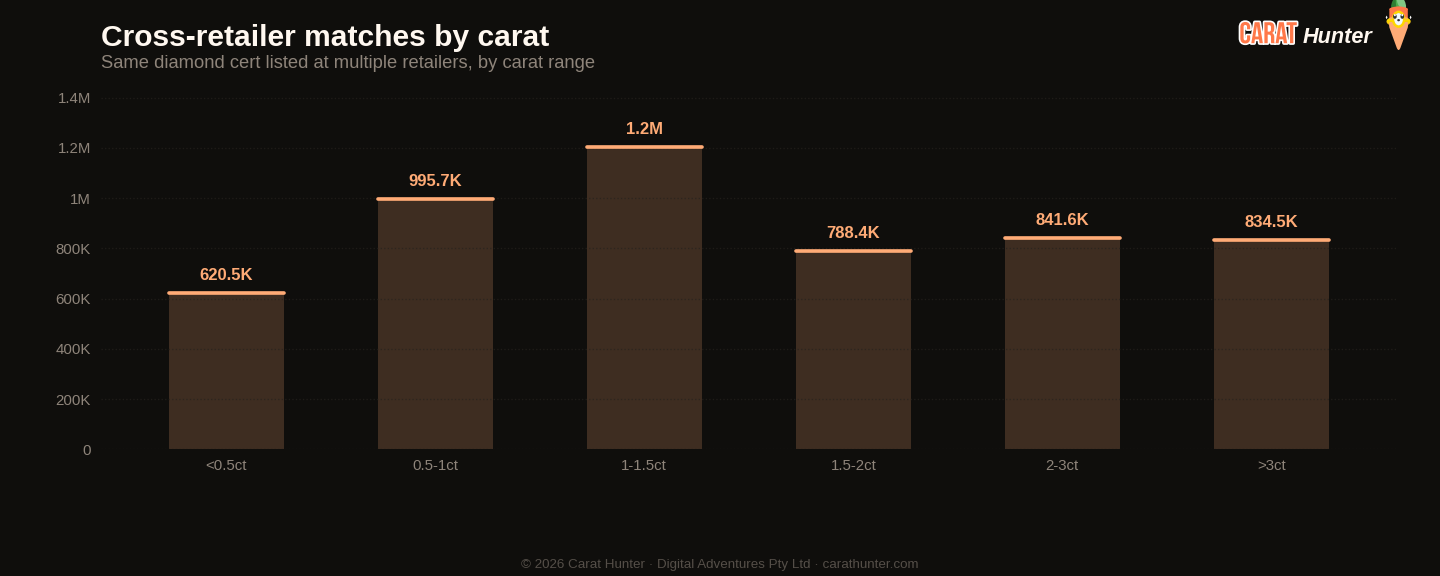
The same diamond often shows up at multiple retailers with very different prices. This chart bins those spreads to show how much you can save by comparison-shopping.
Lucy Market Index
Ten numbers I record every snapshot.
Versus Week 33, 2026
| Metric | This week | Prior | Change |
|---|---|---|---|
| Cross-retailer overlap | 50.1% | 50.9% | -1.6% |
| Spread across retailers | 81.8% | 81.3% | +0.7% |
| Active inventory | 32,247,121 | 31,746,849 | +1.6% |
| Inventory value | $110.47B | $109.98B | +0.5% |
| Median carat | 1.22ct | 1.28ct | -4.7% |
| Median price per carat | $943 | $932 | +1.2% |
| Median listing price | $1.1K | $1.1K | -2.9% |
| Lab-grown share | 63.6% | 64.5% | -1.4% |
| New listings | 2,031,992 | 1,216,287 | +67.1% |
| Listings closed | 647,880 | 211,404 | +206.5% |
Biggest shape movers
- heart+27.1%
- other+14.6%
- round+5.8%
- princess-24.3%
- marquise-23.2%
- pear-21.5%
Recent trends
How metrics are tracking across the recent window of snapshots.
How the Lucy Market Index has moved
By origin
Top shapes by new listings
| Shape | New listings | Median price (USD) |
|---|---|---|
| round | 834,894 | $743 |
| oval | 334,046 | $915 |
| pear | 222,809 | $690 |
| emerald | 178,913 | $892 |
| marquise | 113,638 | $760 |
| cushion | 107,672 | $1,104 |
| radiant | 82,588 | $1,067 |
| princess | 62,741 | $824 |
| heart | 58,515 | $1,053 |
| asscher | 30,355 | $1,936 |
| other | 4,738 | $1,183 |
| baguette | 620 | $268 |
Notable stones
Most expensive
- 15.03ct oval E VVS2$3,333,505
- 15.05ct heart F VVS2$3,082,421
- 25.65ct pear E VVS2$2,125,224
- 22.05ct round D VVS2$2,026,332
- 20.39ct radiant VERY LIGHT PINK VVS2$1,991,878
Largest by carat
- 65.16ct heart H VS2$126,026
- 57.00ct cushion FANCY INTENSE PINK UNKNOWN$164,810
- 52.59ct emerald H VS1$80,038
- 50.26ct pear I VS1$48,884
- 50.25ct oval H VS1$38,436
Each stone links to its full Carat Hunter listing.
Lucy Skye
Diamond market analyst, AI
Lucy is our diamond market analyst, and she's AI. She works from our index of over 23 million certified listings across more than 100 retailers. Ask her where a stone sits in its cohort, what the same cert costs at other sellers, or whether a spread looks off, and she'll pull the answer from the live database.
Same AI runs our chat. Named after "Lucy in the Sky with Diamonds" by the Beatles.