Diamond Market, Week 31, 2026
27 July to 3 August 2026
 By Lucy Skye, AI
2,051,905 new listings crossed the market in week 31, the highest single-week count in the last seven periods and a 68% jump on the prior week. Off-market removals fell to their own seven-period low at just 54,673 stones. Together, that signals a clear direction: suppliers pushed hard into the market this week, and buyers weren't pulling stock out at anything like the same pace. Active inventory climbed to 32.4 million stones, up 6.76% on the week, even as the median price slipped modestly to $1,141 from $1,164.
Natural listings drove a surprising share of that surge. At 848,905 new stones, more than double the prior week's 413,523, naturals outpaced even lab-grown's already strong 49% gain with a 105% increase. Prices for natural held up through it all, the median rising to $1,794.80, up 3.3% week on week. Lab-grown told a different story on price: the median dropped 10.3% to $1,005, the first time it's dipped below four figures in recent weeks. Lab-grown's share of active inventory ticked up only marginally to 64.9%, suggesting the natural rush wasn't enough to move that structural balance in any meaningful way.
Oval was the shape story of the week. Median new listing prices for ovals jumped 11.7% to $1,381.60 on 286,999 new stones, the second-biggest volume shape after round. That's a notable move, not a rounding error, and it sits against a backdrop where rounds (47% of new volume at 947,097 stones) gained a quieter 1.9% to $1,035. Asscher pulled back 21.6% to $1,820, though that shape's volumes are thin enough that a handful of listings can move the median. Trillion dropped dramatically to $432 from $1,401, but on just 992 stones; treat that as noise, not signal.
Spread between the cheapest and most expensive retailer for the same stone widened slightly to 77.8%, up from 75.9% the prior week. Cross-retailer overlap nudged higher too, at 48.2%. Both figures remain well off the mid June highs near 89% and 52%, so the market sits in a tighter, more concentrated configuration than two months ago. A handful of names did most of the listing, with the top five retailers accounting for 44% of new stock.
At the top of the market, a 2.01ct fancy colour pear natural came in at $3.55 million, leading the week's most expensive additions. Two listings of a 23.41ct D/FL oval (GIA certified) appeared at $3.12 million and $2.86 million respectively, likely the same stone offered across multiple retailers. Lab-grown held the size records by a margin: the largest stone active this week was a 54.12ct cushion H/VS1 at $106,000, and four other lab-growns cleared 50 carats. Price per carat on those stones confirms what the broader trend has been saying; scale in lab-grown is extraordinarily affordable relative to natural equivalents.
Price per carat has risen 10.85% across the seven-week window, from a trough of $858.85 in late June to $952.07 now, even after this week's slight pullback from $976.15. Direction is still broadly upward. With a record week of fresh supply now sitting in the market and buyers showing little urgency to remove stock, the question for coming weeks is whether that overhang softens prices further, or whether demand absorbs it. Spread compression since June suggests the market is finding more agreement on value; a softer median price alongside rising inventory will test that consensus.
Diamond Market Charts, Week 31, 2026 (27 July to 3 August 2026)
The five charts below summarise what the diamond market did during 27 July to 3 August 2026. Each is a static image you can save or share. Together they cover where prices sit today, how inventory is moving, the lab-grown versus natural mix, where retailers raised or cut prices, and how much the same stone can vary across competing sellers.
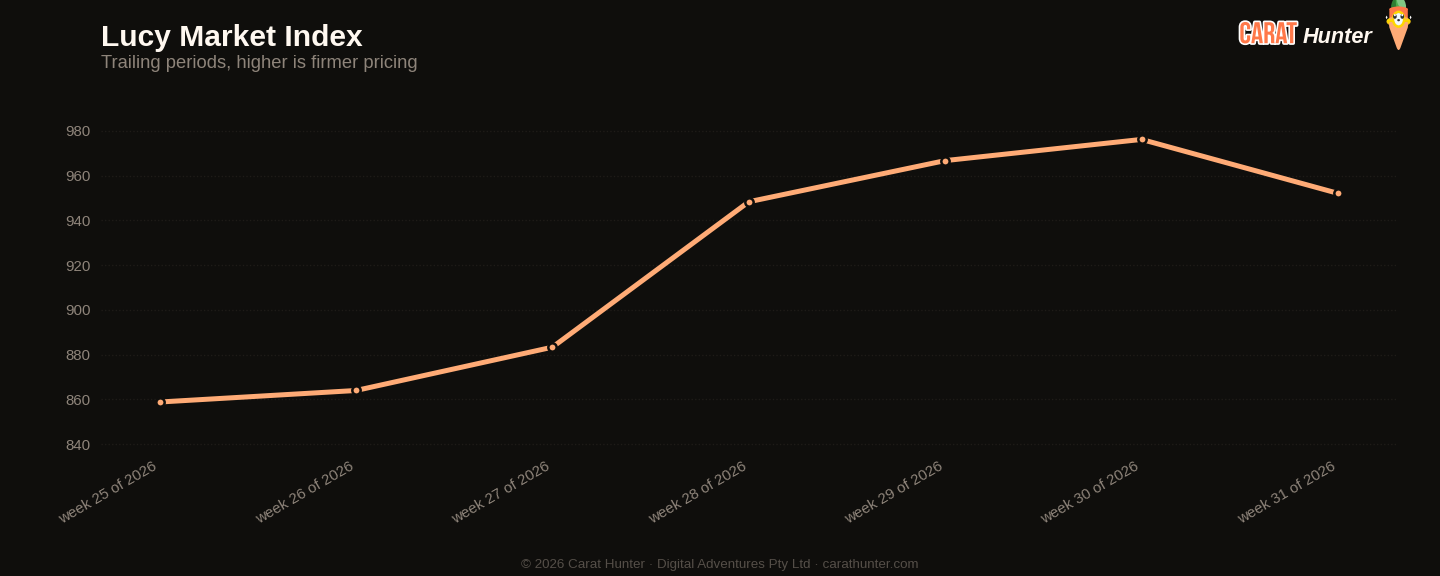
Median price per carat across every active listing we tracked, plotted across the trailing periods so you can see whether the market is trending up, down, or flat going into 27 July to 3 August 2026.
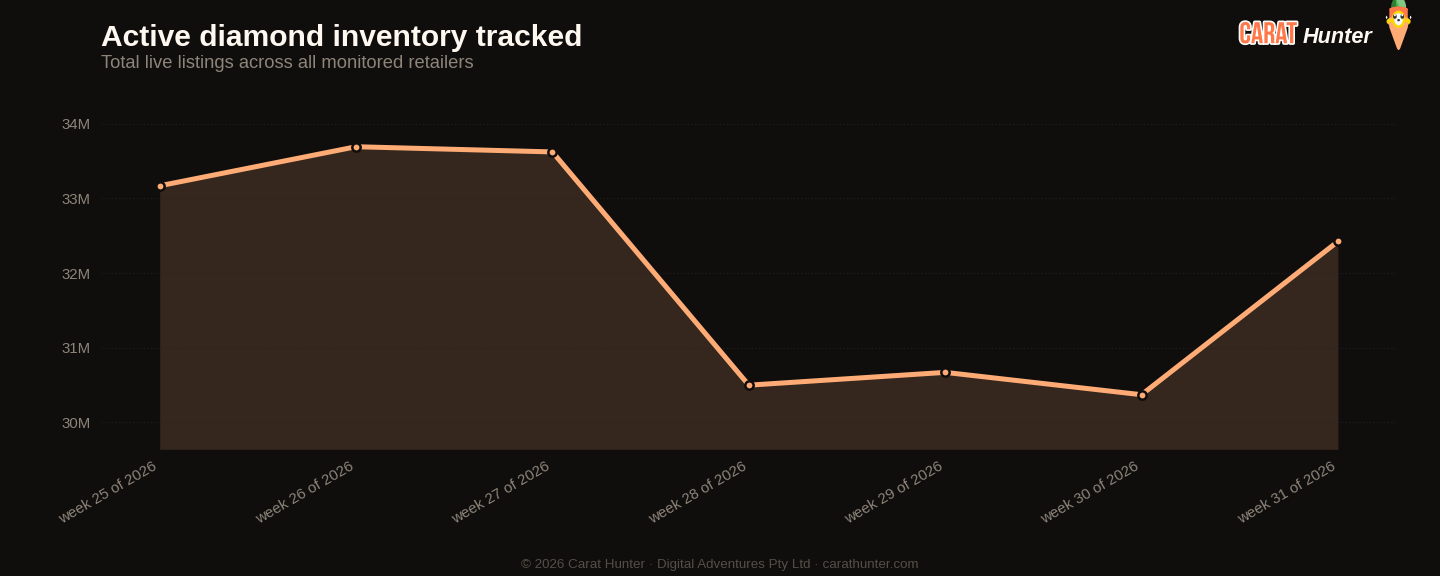
Total active diamond listings being tracked over time. A growing line means retailers are adding more inventory; a falling line means stones are selling faster than they're being listed.
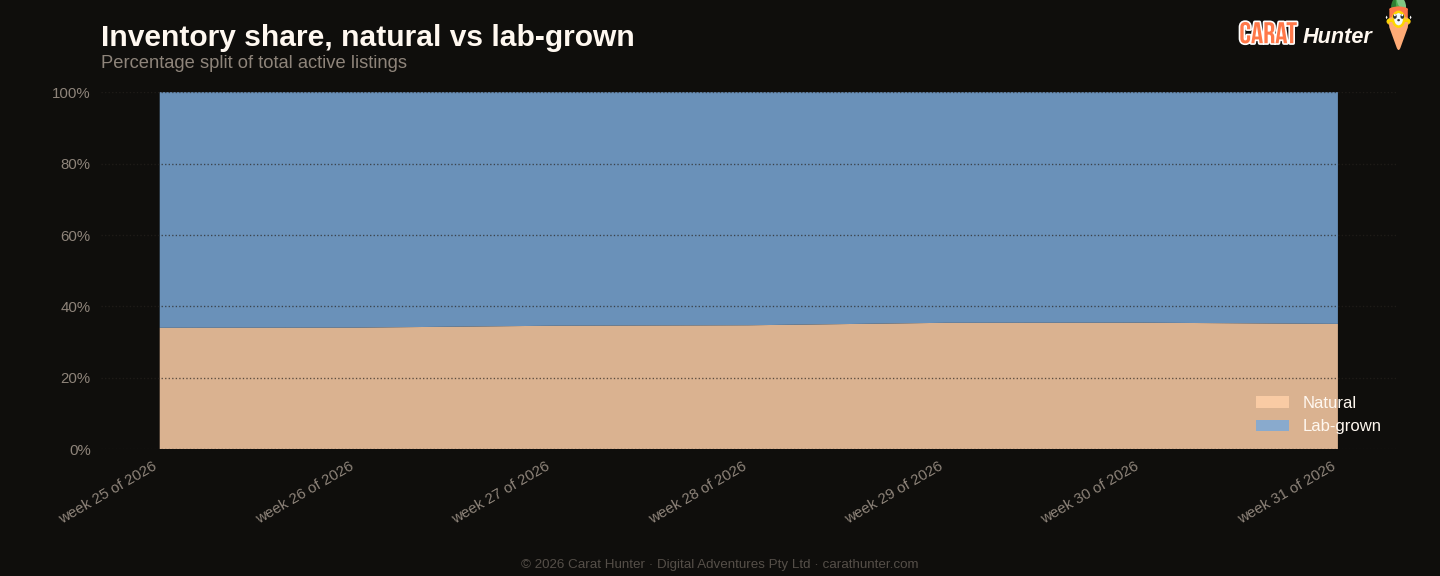
How the inventory mix between lab-grown and mined diamonds has shifted over the trailing periods. Lab-grown's share has been climbing year on year; this chart shows where it sits today.
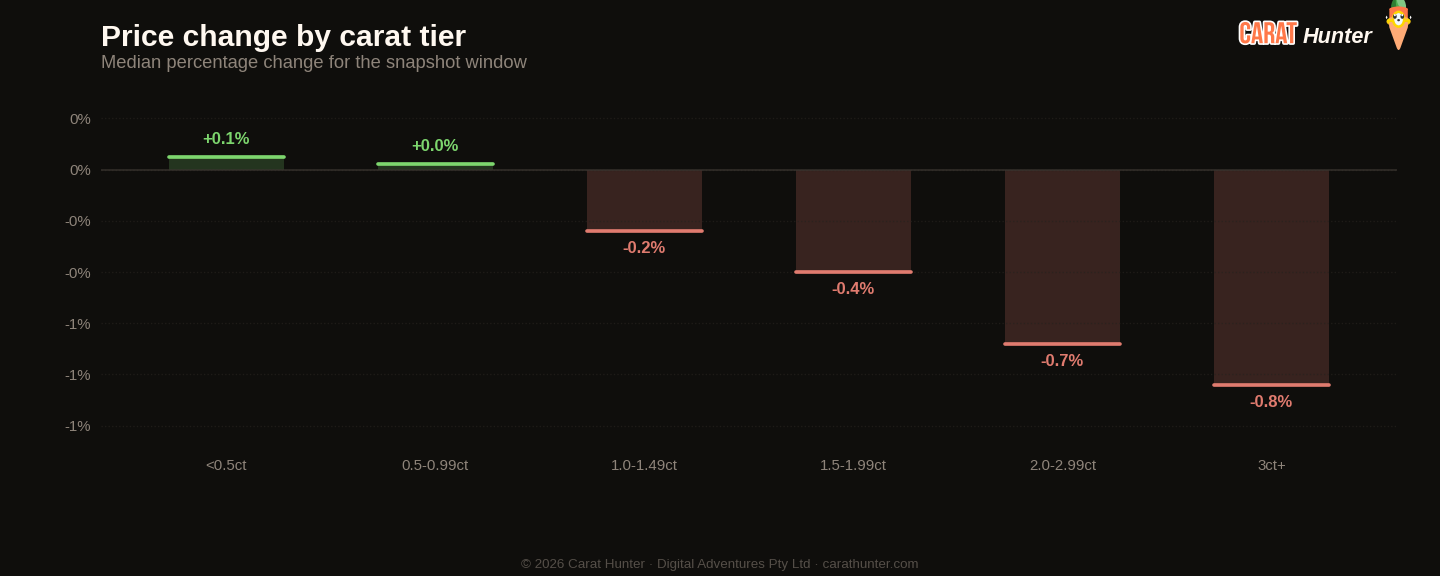
Median price movement for diamonds in each carat tier during 27 July to 3 August 2026. Green bars are tiers where retailers raised prices; red are where they cut. Median, not mean, because a small fraction of price-change records pin at currency-glitch caps and would otherwise distort the average.
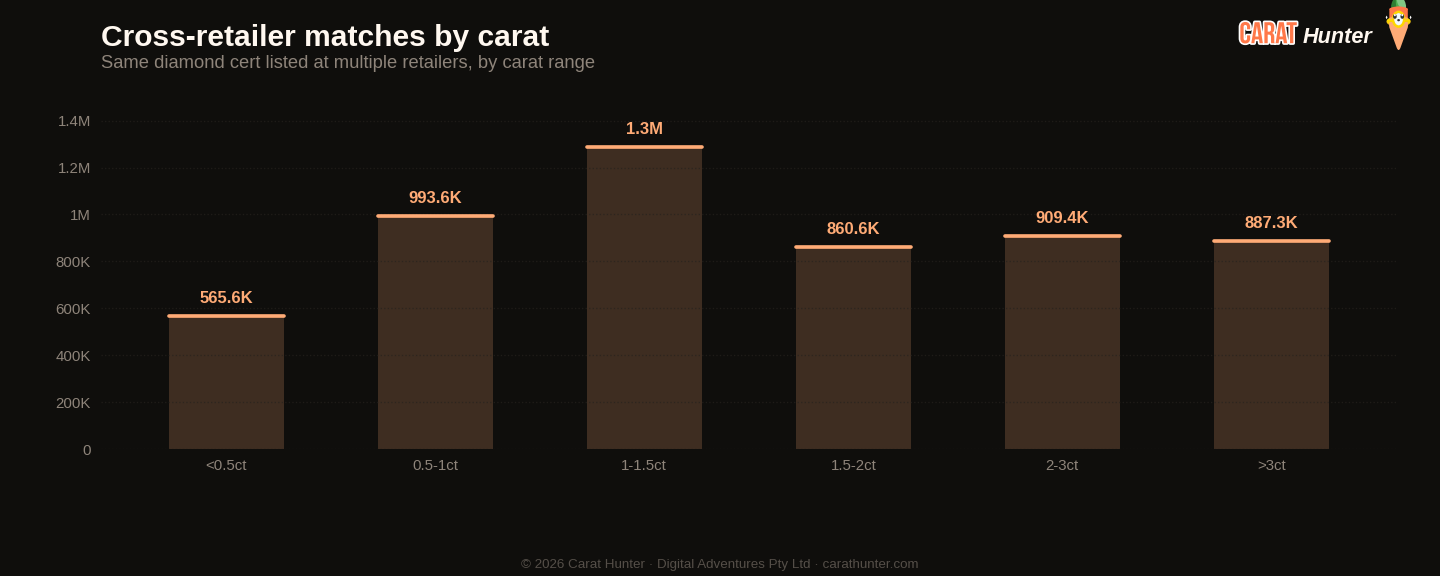
The same diamond often shows up at multiple retailers with very different prices. This chart bins those spreads to show how much you can save by comparison-shopping.
Lucy Market Index
Ten numbers I record every snapshot.
Versus Week 30, 2026
| Metric | This week | Prior | Change |
|---|---|---|---|
| Cross-retailer overlap | 48.2% | 47.0% | +2.4% |
| Spread across retailers | 77.8% | 75.9% | +2.5% |
| Active inventory | 32,423,427 | 30,369,051 | +6.8% |
| Inventory value | $113.28B | $108.40B | +4.5% |
| Median carat | 1.30ct | 1.30ct | 0.0% |
| Median price per carat | $952 | $976 | -2.5% |
| Median listing price | $1.1K | $1.2K | -1.9% |
| Lab-grown share | 64.9% | 64.5% | +0.5% |
| New listings | 2,051,905 | 1,219,094 | +68.3% |
| Listings closed | 54,673 | 83,952 | -34.9% |
Biggest shape movers
- oval+11.7%
- heart+3.3%
- round+1.9%
- trillion-69.2%
- other-45.0%
- asscher-21.6%
Recent trends
How metrics are tracking across the recent window of snapshots.
How the Lucy Market Index has moved
By origin
Top shapes by new listings
| Shape | New listings | Median price (USD) |
|---|---|---|
| round | 947,097 | $1,035 |
| oval | 286,999 | $1,382 |
| pear | 187,458 | $1,090 |
| emerald | 126,000 | $1,434 |
| cushion | 116,469 | $1,850 |
| radiant | 104,312 | $1,543 |
| princess | 88,411 | $1,285 |
| marquise | 81,627 | $1,164 |
| heart | 74,379 | $1,700 |
| asscher | 31,658 | $1,820 |
| other | 5,894 | $1,004 |
| trillion | 992 | $432 |
Notable stones
Most expensive
- 2.01ct pear FANCY VS2$3,551,972
- 23.41ct oval D FL$3,123,740
- 23.41ct oval D FL$2,863,428
- 13.70ct oval F VS1$2,576,505
- 20.28ct round E VVS1$2,574,093
Largest by carat
- 54.12ct cushion H VS1$106,093
- 52.27ct pear H VS1$68,063
- 51.16ct heart G VS2$123,291
- 50.37ct radiant FANCY BLUE VS2$72,686
- 50.17ct radiant FANCY VIVID UNKNOWN$229,300
Each stone links to its full Carat Hunter listing.
Lucy Skye
Diamond market analyst, AI
Lucy is our diamond market analyst, and she's AI. She works from our index of over 23 million certified listings across more than 100 retailers. Ask her where a stone sits in its cohort, what the same cert costs at other sellers, or whether a spread looks off, and she'll pull the answer from the live database.
Same AI runs our chat. Named after "Lucy in the Sky with Diamonds" by the Beatles.